GLOBAL RICARDI Avocats
45 minutes · no commitment FR Book my slot
Maître Julien Pateoueille, French Tax Code in hand
Maître Julien Pateoueille Tax lawyer
Owners of SMEs and mid-market companies · sell tomorrow, or step back from operations now

The more the company depends on you, the less it is worth

Stepping back from operations improves your quality of life today — and raises the price on the day you sell. It is the same work.

Everything goes through you. A buyer sees it before your accounts.
Nothing is written down. What cannot be read becomes a risk.
Structure, tax, processes, key positions: everything is connected.
The sooner it is done, the more you benefit — either way.
  • Member of the Hauts-de-Seine BarToque no. 1733
  • Professional secrecyFrom the very first conversation
  • 45 minutes by video callWith the lawyer who would handle the matter
  • Complimentary, no commitmentNo sales follow-up
  • Written preliminary reportDelivered within 5 working days
  • 5.0 Google rating
They entrusted us with their matter · Google reviews
5.0 Google rating
“Very good support. He took the time to understand my situation and to explain things to me clearly.”
SLU PrestigeGoogle review, translated from French
“A very human lawyer who truly listens to his clients.”
Manon D.Google review, translated from French
“Beyond his unquestionable technical skills, I appreciated how well he listened and how quickly he understood what was at stake for me personally.”
Emma M.Google review, translated from French
“I wanted to leave a review because tax is often a complex and stressful subject, but here I found truly reassuring support.”
Anaëlle G.Google review, translated from French
“One of the best services I have ever received, in any field.”
Romain L.Google review, translated from French
“A professional who listens, with the rigour always to find the right solution!”
Wyl B.Google review, translated from French
“I wanted to reduce my tax burden. The first meeting was excellent: Maître Pateoueille immediately understood my issue and my tax situation.”
Marie-Noëlle G.Google review, translated from French
“An excellent lawyer who quickly grasped my tax issue and gave me a more than relevant answer.”
P. G.Google review, translated from French
“At last, a tax lawyer who lives up to expectations.”
Chantal D.Google review, translated from French
“Excellent support, with expertise I greatly appreciated.”
Emma P.Google review, translated from French
“Precise, professional support, suited to my needs.”
Rayan D.Google review, translated from French
Read the reviews on Google
The path, in three steps

From the first conversation to a company that runs without you

1 Today · 45 min
Book your slot

A video call with the lawyer who would handle the matter — not a salesperson. You leave with a frank opinion, even if the answer is no.

2 Within 5 working days
Receive your written preliminary report

Discount scoring, risk map, value range. The document is yours to keep, even if you go no further.

3 13 weeks
The programme, if it suits your situation

Six workstreams run in parallel, with a 90-minute call each week. At the end: a company that runs without you, and a value case.

01 · Your situation, in 30 seconds

Tick what applies to your company

Each box you tick is a negotiating point the buyer will use. Nothing is sent: this is for you alone.

{{ score }}
of 8 issues
{{ verdict }}
{{ simEbitdaLabel }}
€100,000€3,000,000
An approximate figure is enough. We adjust it precisely during the preliminary assessment — that is often where the first surprise appears.
What your answers take off the price
{{ simEcart }}
a discount of {{ simDecote }}

{{ simPhrase }}

Buyer’s valuation today · {{ simValNow }} Prepared file · {{ simValPrep }}
No boxes ticked: that is the perfectly prepared file. Few companies are already there — tick what genuinely applies to you.

A low, deliberately cautious assumption. This estimate applies market ranges to an average multiple of 5.5×; it takes no account of your sector, the recurrence of your revenue or the acquirer’s profile. It is neither a valuation nor a commitment to a sale price.

Have my issues costed 45 minutes to find out what each one costs you, and in what order to address them.
02 · The paradox

What holds the company together is exactly what drives its value down

You are indispensable: that is what made it grow. But a buyer buys what carries on without you — every decision that comes back up to you becomes a discount.

Today
Your day-to-day involvementhigh
Defensible value of the companylow
Quotes, purchasing, hiring, judgement calls: everything waits for your approval.
After thirteen weeks
Your day-to-day involvementby choice
Defensible value of the companyhigh
The same decisions are written down, delegated, and held by people in secured positions.
What moves the needle
1Legal and tax structure

Holding company, property company, contracts, asset ownership. The structure stops being a sticking point.

2Written processes

Your 8 to 15 critical processes formalised in an operations manual. The company becomes readable.

3Automated processes

Repetitive tasks given the right tools, with your teams. Time freed up, and an organisation that can be replicated.

4Key positions

Indispensable people are identified, prepared and retained.

5Dependence on the owner

Operating procedures, decision rules, internal capsules: your know-how becomes an asset.

6Accounts and value case

Adjusted earnings, supported document by document, and a data room that answers questions before they are asked.

What you gain straight away

Time, a team that makes decisions, and a company that runs without you — even if you never sell.

What you gain on exit

A defensible multiple, a larger share paid at closing, and less of the price made conditional.

Everything is connected: the sooner it is done, the better you live — and the more the company is worth.

What is everything that still depends on you costing you? 45 minutes to put a figure on it.
Book my slot →
03 · Two situations, one method

You want breathing room, or you are selling soon

Both lead to the same work: making the company able to run without you.

Profile 1 — the seller
You want to sell in the coming years

You come to the table with a well-built file, adjusted figures and written answers. You negotiate, rather than having the buyer’s timetable imposed on you.

—A defensible multiple, backed by evidence
—A larger share paid at closing
—Less earn-out, fewer warranties imposed
Profile 2 — the owner still in post
You have no date in mind, but you want to step back from day-to-day operations

You win back room in your week, your managers become more autonomous, and the company’s value rises at the same time. A sale remains an option, not an obligation.

—Working days that no longer hinge on your decisions
—A margin that no longer depends on your hours
—A legal and tax structure already in order

The work is the same. Only the exit date changes.

You do not know what you are losing until someone has measured it.
Book my slot
04 · The problem

Twenty-five years. Seventy hours a week.

One day, you will want to hand over. Without selling short what you have built.

01

Weekends sacrificed, and decisions taken alone on Sunday evenings.

02

A company that holds together because you are there, every day.

03

Know-how that no one has ever written down, and that lives in your head.

04

And no one across the table measuring what it has cost.

Price

Commensurate with the effort. Not the first figure a buyer puts on the table.

Time

Winning back room in your week, before a sale is even discussed.

What comes next

An exit that looks like the one you imagined. Chosen, not imposed.

Support

Being advised by people who have already carried out these transactions, and who tell you plainly.

On the day of the sale, none of this shows in the price. Unless the file has been prepared.

05 · The reality

A buyer calls you. Here is what happens, in order.

Nothing hostile: the normal mechanics of an acquisition — which work against an unprepared file.

01
The approach

The timetable becomes the buyer’s.

02
The letter of intent

An indicative price, subject to conditions. It is the figure you will remember.

03
Due diligence

Accounts, contracts, key people. Every grey area becomes a negotiating point.

04
The warranties

What you warrant, and for how long.

05
Closing

And the headline price is not paid in a single sum.

06
Afterwards

12 to 24 months of imposed transition support, if the company does not hold up without you.

What is actually paid on closing day — example
58% paid at closing
The only share you truly control.
17% in escrow
Held back for the warranty period.
25% conditional
Earn-out, vendor loan, transition support.

The stronger your file, the larger the share paid at closing.

The day the buyer calls, your file is ready — or it is negotiated against you.
Prepare my file →
06 · The figures

Dependence on the owner comes at a price, and it can be quantified

4 weeks

of absence, phone switched off: what happens?

The answer is already a value estimate: what the buyer is buying is a cash flow that continues after you leave.

6 in 10

SMEs with 10 to 49 employees concentrate their critical decisions on a single person.

Bpifrance Le Lab, 2023
What the buyer then requires
—Earn-out over 12 to 36 months
—Vendor loan, part of the price made conditional
Owner dependence score
Week 1 78
Week 13 32
Example reading of the scoring built during the programme, measured at the start and at the end.
15–40%

discount on the multiple when the owner is deemed irreplaceable. It is the buyer’s first negotiating point, and it can be dealt with in advance.

France Invest, French mid-market, 2022-2024; Bpifrance.
Objection — “I am the company.”

The point is not to replace you, but to document what can be documented. Covering everything is never the aim; reaching the threshold of credibility for a buyer is.

07 · Understanding

How a company is valued, in practice

Your adjusted earnings
Normalised EBITDA
×
The programme’s playing field
Multiple granted
−
What is deducted
Net debt, adjustments
=
What you receive
Value of your shares
Where your multiple sits, depending on the business profile
Traditional sectors
4–6×
Structured mid-market
8.3×
Recurring-revenue, well-tooled businesses
8–12×
Sources: SME sector benchmarks 2025-2026 · Argos Index mid-market, Q4 2025 · Dealsuite data

You will not change your earnings in thirteen weeks. You will change the multiple.

The gap, in a typical case — same company, same earnings
Industrial SME · normalised EBITDA €620k · constant net debt
Today
dependent on the owner · 4.2×
€2.60m
Prepared
runs without the owner · 5.8×
€3.60m
≈ +€1.0m
difference in value, without a single extra euro of revenue. This is what the preliminary assessment quantifies for your company, item by item.

And how a prepared company is broken down

Often today
A single company
The business The premises The brand The cash
The buyer must take everything, or renegotiate everything.
Prepared structure
Holding company — you hold the shares
Operating company
The business: what is sold.
Property company
The premises, which remain yours.
Brand & assets
What can be licensed or sold separately.
Your multiple can be prepared. The first step is a 45-minute conversation.
Speak to a lawyer
08 · In detail

The discounts are always the same, and each has its own workstream

What the buyer takes off the price, the order of magnitude of each discount, and the workstream that closes it.

{{ d.num }}
{{ d.titre }}
{{ d.chantier }}

Six workstreams run in parallel, not in sequence

The legal work starts first because it depends on third parties. The operational audit feeds into all the others. The value case cannot begin until week 11.

W1
W2
W3
W4
W5
W6
W7
W8
W9
W10
W11
W12
W13
{{ r.num }} {{ r.nom }}
{{ c.num }} {{ c.nom }}

{{ c.desc }}

{{ c.semaines }}
Six workstreams, thirteen weeks. The starting point is a conversation.
Book my slot
09 · The first step

What you receive, before any commitment

A 45-minute conversation, then a document delivered within 5 working days. It is useful to you even if you go no further.

01 · Scoring on 5 dimensions

Legal, operational, people, data and AI, financial.

02 · Risk map

What due diligence will find, ranked by impact and likelihood.

03 · Quantified value gap

The multiple you can defend today, and the one the programme aims for.

04 · Roadmap

The thirteen weeks, the order of work and the expected workload.
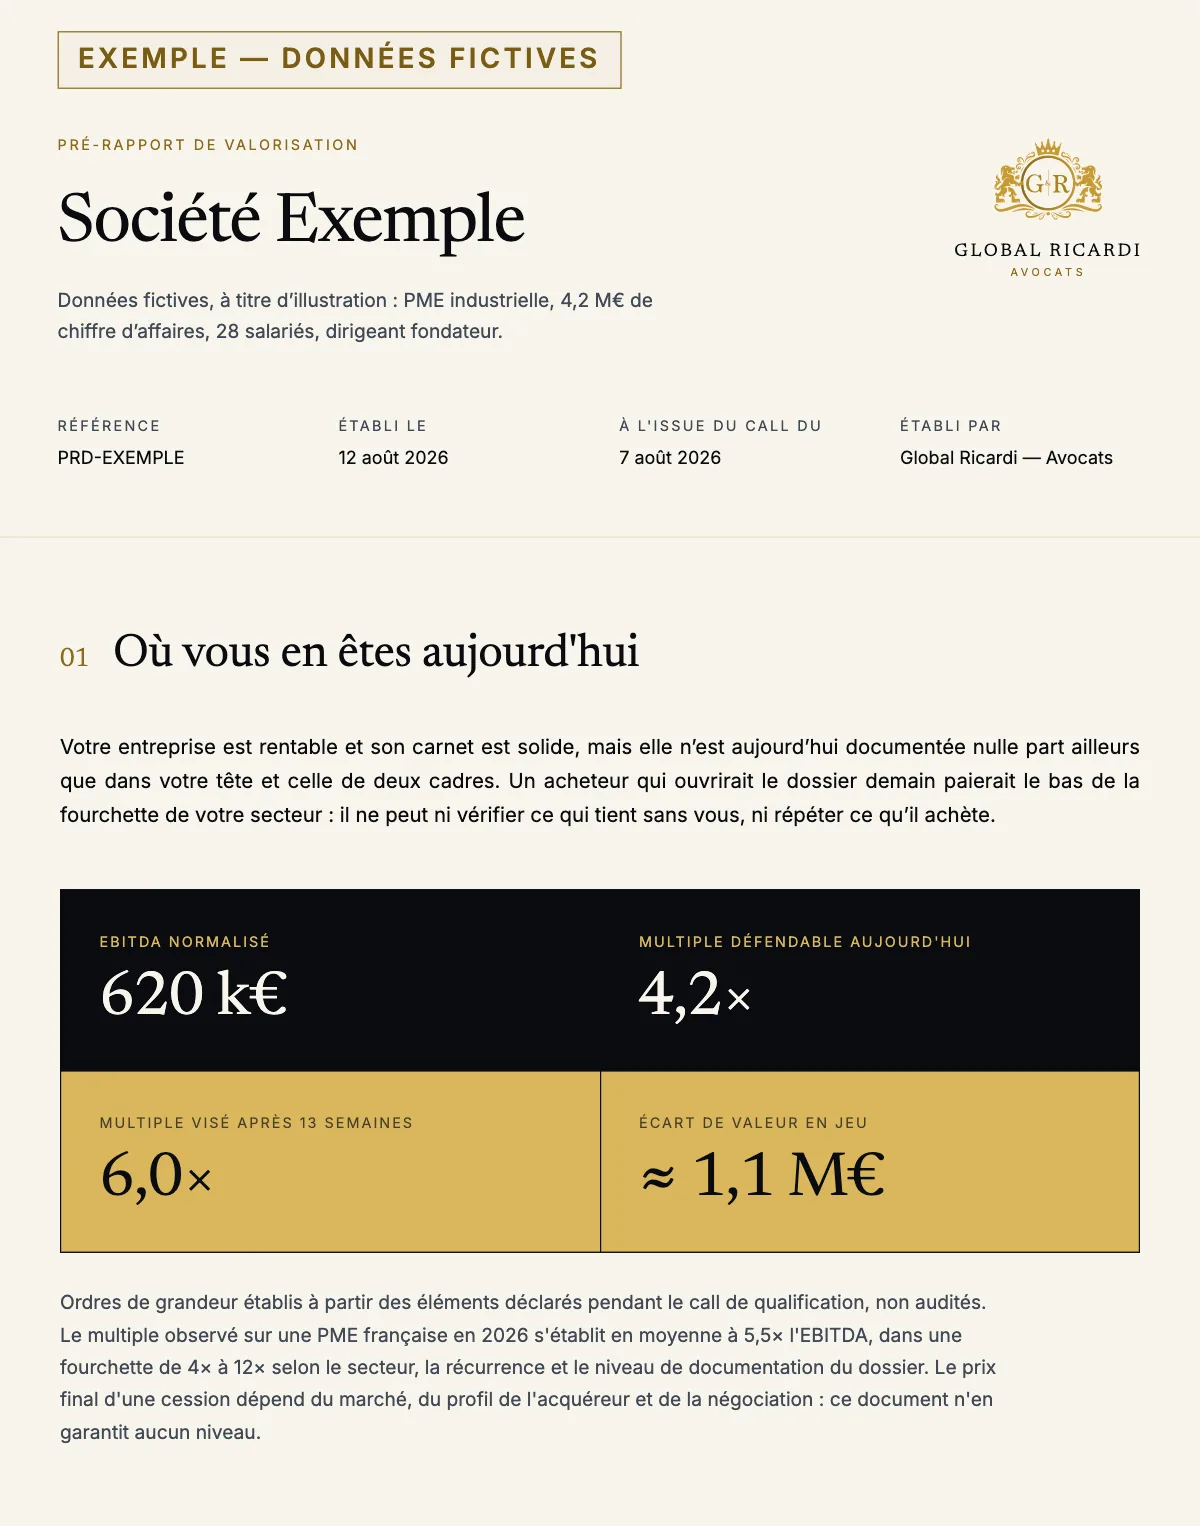
First page of a preliminary valuation report, prepared as an example using fictitious data
Example — fictitious data. The first page of the preliminary report, as delivered.
The preliminary assessment measures how readable and defensible your value is. It guarantees neither that a sale will take place nor any price level: the final price depends on the market, the acquirer’s profile and the negotiation.
The document is yours to keep, even if you go no further.
Get my preliminary report
10 · Support

This is not a report handed to you. It is a company you transform.

The weekly call

90 minutes in a fixed slot. We decide and work jointly on the current deliverable.

Our templates

Ready-to-complete documents and analysis grids to make progress between sessions.

Your team

An internal lead, and your key managers on workstreams 2, 4 and 5. The work stays in-house.

The written summary

Within 24 hours: decisions recorded, an action plan of no more than 5 tasks, red flags.
20% on calls — 90 minutes a week 80% guided production — 4 to 7 hours a week, including the internal lead
Maître Julien Pateoueille, founding lawyer of Global Ricardi
Your partner for the thirteen weeks

A specialist who has already handled these transactions, on both sides of the table

Maître Julien Pateoueille — tax lawyer, top of class in business taxation

Holding companies, LBOs, sales, group reorganisations: he has handled these matters on both sides of the table. He knows where an acquirer applies pressure to bring the price down — and, over thirteen weeks, he weighs the decisions with you.

Around him, a corporate lawyer, a valuation expert and an employment law expert, brought in as the workstreams require — and for you, a single point of contact through to signing.

€120m+
over €120 million in transactions advised on.
+30 to 40%
in value gained on matters prepared ahead of time rather than in a rush.
120
business owners and groups advised, across advisory and litigation work.
2 practices
International tax and M&A, combined in a single point of contact.
Best Tax Specialist Award 2023 IFA finalist — French Senate, 2024 Top of class
Member of the Hauts-de-Seine Bar
Toque no. 1733
Tour First, 1 place des Saisons
92400 Courbevoie — La Défense, France
julien@global-ricardi.com
+33 6 42 27 40 13
The lawyer who would handle your matter conducts the preliminary assessment personally. Complimentary.
Book my preliminary assessment →
11 · In our clients’ words

What our clients say

Excerpts from reviews published on the firm’s Google listing, across all types of engagement.

★★★★★
“I wanted to reduce my tax burden. The first meeting was excellent: Maître Pateoueille immediately understood my issue and my tax situation.”
Marie-Noëlle G.Google review, translated from French
★★★★★
“Beyond his unquestionable technical skills, I appreciated how well he listened and how quickly he understood what was at stake for me personally.”
Emma M.Google review, translated from French
★★★★★
“An excellent lawyer who quickly grasped my tax issue and gave me a more than relevant answer.”
P. G.Google review, translated from French
★★★★★
“I wanted to leave a review because tax is often a complex and stressful subject, but here I found truly reassuring support.”
Anaëlle G.Google review, translated from French
★★★★★
“A professional who listens, with the rigour always to find the right solution!”
Wyl B.Google review, translated from French
★★★★★
“A very human lawyer who truly listens to his clients.”
Manon D.Google review, translated from French
12 · Your questions

The objections we hear

13 · The price, plainly

The preliminary assessment is complimentary. And it stays that way.

No free trial that turns into a paid one, no sales follow-up. A conversation, a written document, and a decision that is yours.

What it costs you
€0
✓45 minutes by video call, with the lawyer who would handle the matter
✓Written preliminary report within 5 working days, yours to keep
✓Value range and discounts quantified in euros
✓A frank opinion — even if the answer is no
What you come away knowing
01Where your value is leaking, item by item
02What each leak costs, in euros
03The order in which to address them, and over how many weeks
04Whether the programme makes sense for you — or not
You are 5 working days away from your preliminary report
1
Choose a slot
Two minutes, in the calendar below.
2
The 45-minute call
Dependence, contracts, structure, accounts.
3
The preliminary report
Written, quantified, within 5 working days.
4
Your decision
The programme, or not. No chasing.
5
The 13 weeks
Six workstreams, one deliverable a week.
Your point of contact
JP
Maître Julien Pateoueille
Member of the Hauts-de-Seine Bar · toque 1733

He conducts the preliminary assessment himself, and he would handle the matter. Not a salesperson.

+33 6 42 27 40 13 julien@global-ricardi.com
Reply within 24 working hours · lawyer’s duty of professional secrecy
14 · Next step

Know what your company is worth, before someone else tells you

Three steps before you commit. You remain in control of the timetable and the decision.

01
An initial conversation — 45 minutes. We check that the programme makes sense for you, and we say so frankly if it does not.
02
The preliminary report. Where your company is being discounted, by how much, and in what order to address the issues.
03
Getting started, if you so decide. A fixed slot each week, an internal lead on your side, and the thirteen weeks are under way.
The programme makes your value easier to read and easier to defend; it guarantees neither that a sale will take place nor any price level.
Book my slot
WhatsApp